TDS/TCS Payment Due Date for September 2026 – 7 October 2026
# TDS/TCS Payment Due Date for September 2026 – Important Compliance Reminder for Businesses
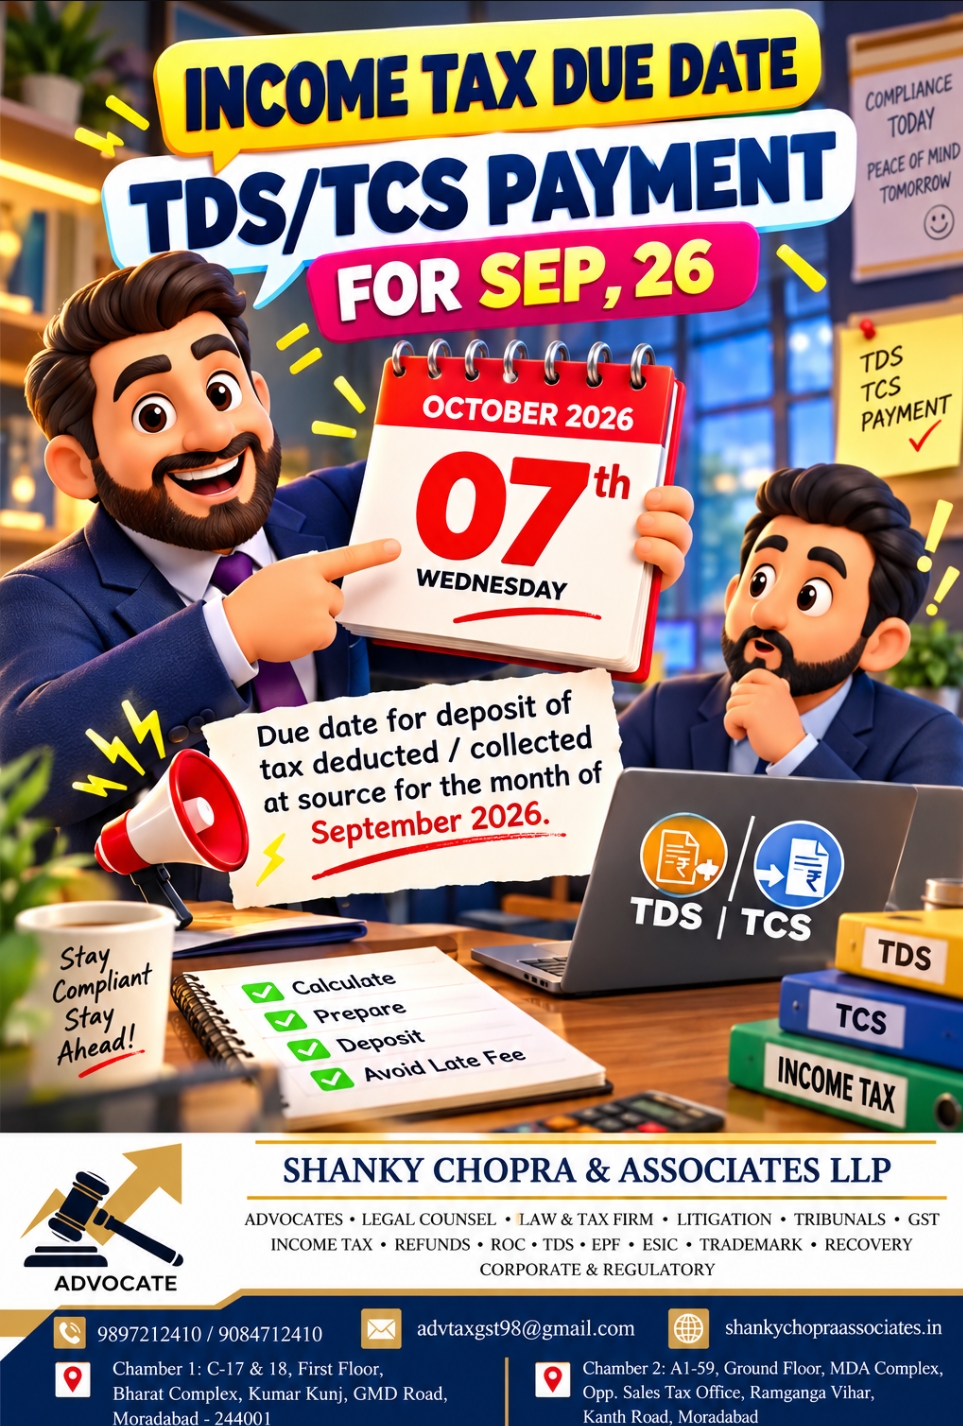
**TDS/TCS Payment Due Date: 7 October 2026**
Businesses, employers, professionals, companies, firms and other persons responsible for deducting or collecting tax should pay close attention to their monthly TDS and TCS compliance. For tax deducted or collected during **September 2026**, the applicable general due date for deposit is **7 October 2026**.
The Income Tax Department has continued the general monthly payment timeline under the **Income-tax Act, 2025 and Income-tax Rules, 2026**. For TDS deducted from April to February, the general due date remains the 7th of the following month. ([Income Tax India][1])
Accordingly, tax deducted or collected during September 2026 should be reviewed and deposited within the prescribed time.
## What is TDS?
TDS stands for **Tax Deducted at Source**. It is a mechanism through which tax is deducted by the person responsible for making certain specified payments and deposited with the Central Government.
TDS provisions may apply to various payments, depending upon the nature of the transaction, the status of the payer and recipient, applicable thresholds and other conditions prescribed under the Income-tax law.
Common transactions where TDS compliance may arise include:
* Salary payments
* Contractor and subcontractor payments
* Professional or technical fees
* Rent payments
* Commission and brokerage
* Interest payments
* Certain payments to residents and non-residents
* Certain specified transactions covered by the applicable TDS provisions
The person responsible for deduction must determine whether TDS is applicable, identify the correct provision and rate, deduct the appropriate amount and deposit the tax within the prescribed timeline.
## What is TCS?
TCS stands for **Tax Collected at Source**. Under applicable provisions, a seller or other specified person may be required to collect tax from the buyer or other specified person in respect of prescribed transactions.
TCS provisions apply to specified transactions and categories covered by the Income-tax law. Therefore, businesses involved in transactions subject to TCS should maintain proper records and ensure that the amount collected is deposited within the applicable due date.
For businesses handling both TDS and TCS, monthly reconciliation is particularly important because the nature of transactions, applicable provisions and reporting requirements can differ.
## September 2026 TDS/TCS Payment Due Date
For the September 2026 tax deduction/collection period, the key compliance date is:
**Month of deduction/collection:** September 2026
**Due date for general monthly deposit:** **7 October 2026**
The Income Tax Department's tax calendar follows the monthly payment schedule, with tax deducted or collected during a month generally becoming due for deposit on the 7th of the following month. ([Etds][2])
Therefore, businesses should not wait until the last moment to calculate their liability.
## Why businesses should complete the compliance on time
TDS and TCS are not simply accounting entries. Once tax has been deducted or collected, the person responsible has an obligation to deposit the amount with the Government within the prescribed period.
Delay can result in interest and other consequences under the applicable provisions.
The Income Tax Department explains that delay in payment of TDS after deduction can attract interest, while delay in payment of TCS after collection can also result in interest. ([Etds][3])
Therefore, a business should ideally complete the following steps before the due date:
1. Identify all transactions liable to TDS/TCS.
2. Verify the applicable provision.
3. Check the applicable threshold and rate.
4. Verify PAN and other relevant details.
5. Calculate the amount correctly.
6. Reconcile the amount with the books of account.
7. Generate the appropriate challan/payment details.
8. Deposit the amount within the prescribed time.
9. Preserve the payment challan and supporting records.
10. Reconcile the payment with subsequent TDS/TCS reporting.
## Common TDS compliance mistakes
Even businesses that regularly deduct TDS can make errors in monthly compliance. Some of the common issues include incorrect deduction rates, missed transactions, incorrect PAN details, wrong nature of payment, incorrect challan details and failure to reconcile the books with the TDS workings.
For example, a business may make several professional payments during a month but fail to include one or more transactions while preparing its TDS working. Similarly, payments recorded under different accounting heads may require additional review before determining whether TDS applies.
Another common issue is the difference between the date of booking an expense and the date of payment or credit. Since TDS provisions can operate based on specific statutory conditions, the transaction should be examined according to the applicable provision rather than merely relying on the accounting entry.
## TDS/TCS reconciliation is important
Monthly reconciliation can significantly reduce the possibility of future discrepancies.
A proper reconciliation may include comparison between:
* Books of accounts
* TDS/TCS working
* Payment records
* Challan details
* PAN details
* Ledger accounts
* Vendor/customer information
* Previous period adjustments
* Applicable statutory provisions
Businesses with a large number of vendors, employees or transactions should maintain a systematic compliance process instead of preparing TDS/TCS payments at the last minute.
## What happens if TDS payment is delayed?
Delay in depositing tax can have financial consequences.
The Income Tax Department's guidance states that interest may arise for delay in payment of TDS after deduction. The applicable interest provisions should be calculated according to the circumstances of the particular default. ([Etds][3])
In addition to interest, prolonged or serious defaults can have other statutory consequences. Accordingly, taxpayers should not treat a delayed TDS/TCS payment merely as a routine accounting adjustment.
Where a default has already occurred, the exact period of delay, amount involved and applicable statutory provision should be examined before making the corrective payment.
## TDS/TCS payment and return filing are different compliances
One important point that businesses should understand is that **depositing TDS/TCS and filing the quarterly statement are separate compliance requirements**.
Payment of tax during the month does not by itself complete the entire TDS/TCS compliance cycle.
After the relevant quarter, the applicable TDS/TCS statement must also be furnished within the prescribed due date. The Income Tax Department specifies separate due dates for TDS and TCS statements. ([Etds][4])
Therefore, businesses should maintain a compliance calendar covering both:
**Monthly:** TDS/TCS calculation and payment
**Quarterly:** TDS/TCS statement filing and related reporting
**Subsequently:** Reconciliation and correction, wherever required
## TDS certificates and reporting
The compliance process does not end with payment. The deductor also has responsibilities relating to reporting and issuance of applicable TDS certificates.
The Income Tax Department identifies payment of tax, filing of periodic TDS/TCS statements and issuance of applicable certificates among the responsibilities of persons liable to deduct or collect tax. ([Etds][5])
This makes accurate record-keeping important for both the deductor and the person from whose payment tax has been deducted or from whom tax has been collected.
## Special transactions may have different timelines
Although **7 October 2026** is the general monthly due date relevant to September 2026 TDS/TCS compliance, taxpayers should not assume that every type of TDS transaction follows exactly the same payment mechanism.
Certain specified transactions have separate challan-cum-statement mechanisms and timelines. The Income Tax Department's guidance specifically notes exceptions for certain provisions, including transactions relating to immovable property, specified rent payments, certain payments by individuals/HUFs and specified virtual digital asset transactions. ([Income Tax Department][6])
Therefore, before making a payment, the taxpayer should identify the exact nature of the transaction and the corresponding statutory requirement.
## New Income-tax Act, 2025 and TDS compliance
The transition to the **Income-tax Act, 2025** has also made it important for taxpayers and professionals to verify the applicable section and rule references for the relevant tax year.
For FY 2026-27, the Income Tax Department has clarified that the general TDS deposit timelines continue without a policy change, with the corresponding payment timeline prescribed under the Income-tax Rules, 2026. ([Income Tax India][1])
Accordingly, taxpayers should use updated forms, provisions and statutory references applicable to the relevant period rather than relying blindly on older compliance material.
## Practical checklist for 7 October 2026
Businesses can use the following checklist for September 2026:
**✔ Review all September transactions**
**✔ Identify TDS applicability**
**✔ Identify TCS applicability**
**✔ Verify PAN and relevant details**
**✔ Check applicable rates and thresholds**
**✔ Prepare TDS/TCS working**
**✔ Reconcile with books**
**✔ Verify previous-period adjustments**
**✔ Deposit the tax by 7 October 2026, wherever the general monthly due date applies**
**✔ Preserve challan/payment proof**
**✔ Maintain records for quarterly statement preparation**
This simple checklist can help reduce avoidable compliance errors.
## Importance for MSMEs and growing businesses
Small and medium-sized businesses often focus primarily on GST, sales, purchases and banking transactions. TDS/TCS compliance can sometimes receive less attention, particularly when the business does not have a dedicated tax department.
However, as the number of vendors, employees, contractors and professional service providers increases, the possibility of TDS-related errors also increases.
A monthly compliance review can therefore be beneficial for MSMEs, companies, partnership firms, LLPs and other organisations.
Instead of waiting for the quarterly return filing period, businesses should ideally reconcile their TDS/TCS data every month.
## Professional TDS and Income Tax Compliance Support
**Shanky Chopra & Associates LLP** provides professional taxation and legal support for businesses, professionals and organisations in matters relating to **TDS, TCS, Income Tax, GST, tax notices, appeals, refunds, ROC/MCA compliance, EPF, ESIC, trademark and tax litigation**.
We assist clients in **Moradabad, Kanth, Delhi and nearby areas** with taxation compliance, documentation, reconciliation and legal support.
For businesses having multiple transactions, regular TDS/TCS compliance review can help identify potential issues before they become larger statutory problems.
## Final Reminder
The **TDS/TCS payment due date for the general monthly September 2026 compliance cycle is 7 October 2026**. Taxpayers responsible for deduction or collection should review their transactions and complete the applicable payment within the prescribed timeline.
The important point is not merely to deposit the tax but to maintain a complete compliance trail consisting of **correct calculation, timely payment, proper records, reconciliation and subsequent statutory reporting**.
Businesses should also remember that different transactions can have different statutory requirements. Therefore, the specific nature of the payment or collection should always be examined before determining the applicable compliance.
**Timely tax compliance helps businesses maintain cleaner records, reduce avoidable interest exposure and minimise the risk of future notices or reconciliation issues.**
### About Shanky Chopra & Associates LLP
**Shanky Chopra & Associates LLP** is a law and tax practice providing professional assistance in taxation, GST, Income Tax, TDS/TCS, litigation, appeals, refunds, ROC/MCA, EPF, ESIC, trademark and corporate regulatory matters.
**Service Areas:** Moradabad | Kanth | Delhi | Nearby Areas
*Disclaimer: This article is intended for general informational and educational purposes. Tax provisions, rates, procedures and due dates may depend upon the nature of the transaction and the applicable law. Readers should verify the provisions applicable to their specific circumstances before taking any compliance action.*
Have Questions? We're Here to Help
Get expert advice from SHANKY CHOPRA & ASSOCIATES LLP. Reach out to discuss your requirements.