TDS Returns Can Now Be Filed Directly on TRACES from Q2 FY 2026–27
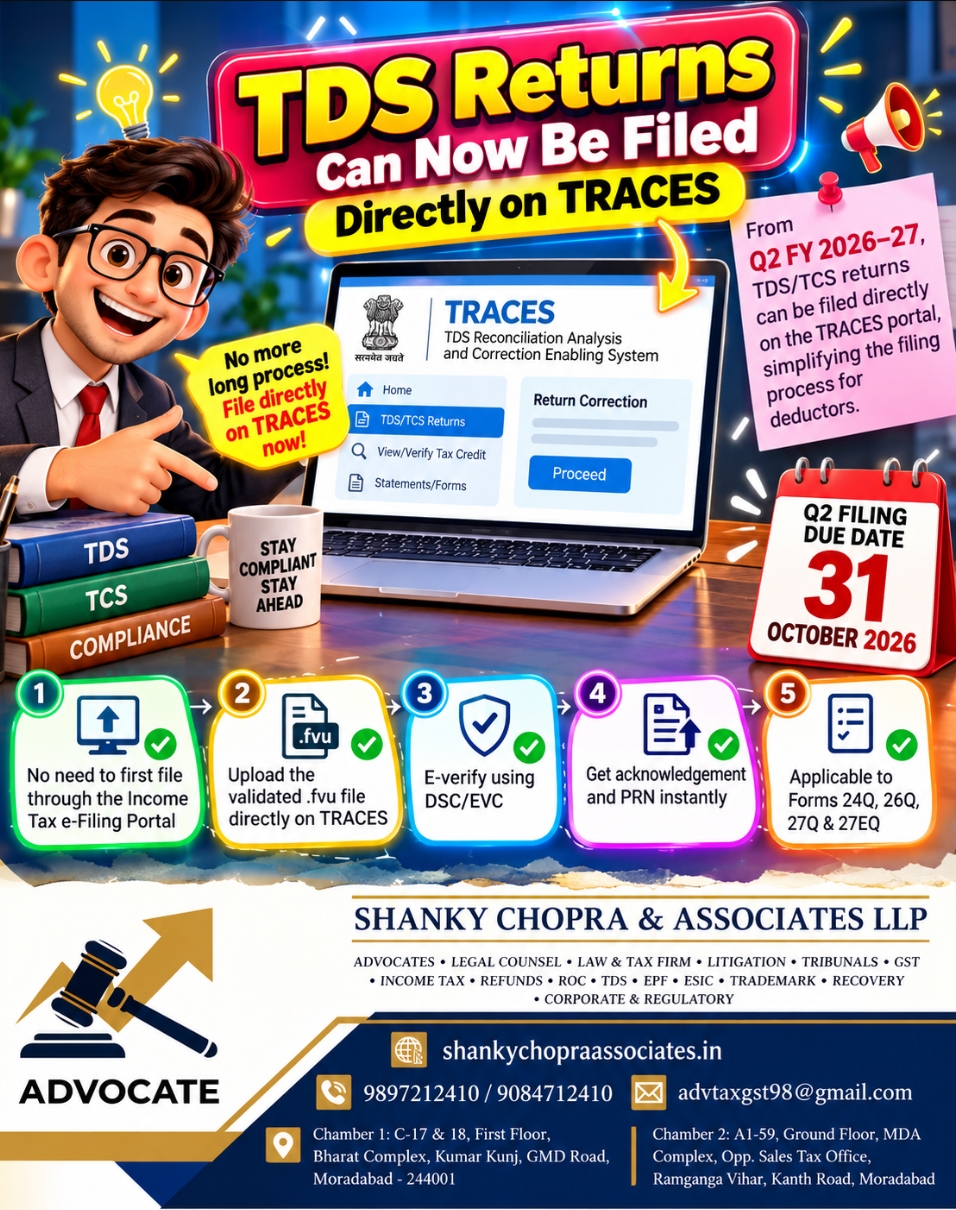
# TDS Returns Can Now Be Filed Directly on TRACES: Important Update for Q2 Tax Year 2026–27
The TDS and TCS compliance process has undergone an important change from **Tax Year 2026–27** following the implementation of the **Income-tax Act, 2025** and the **Income-tax Rules, 2026**.
For the **July–September 2026 quarter (Q2)**, taxpayers and deductors should be particularly careful about the new form numbers, filing procedure and due date. The **Q2 TDS/TCS statement is due on 31 October 2026**. ([Income Tax Department][1])
One of the important procedural developments is the availability of a **direct online filing workflow through the TRACES portal** for the new regime. Recent practitioner guidance reports that, from Q2 onwards, statements can be prepared, validated and filed within the deductor's TRACES login, reducing the need for the earlier separate preparation-and-upload workflow. ([Casa Huja][2])
For businesses, employers, professionals and tax practitioners, this change can make quarterly TDS/TCS compliance more convenient—but it also makes it important to understand exactly which forms apply from 1 April 2026.
---
## What Has Changed from Tax Year 2026–27?
The Income-tax Act, 2025 applies to the new tax regime beginning from **1 April 2026**. As a result, familiar TDS/TCS statement numbers have been renumbered.
The commonly used old forms and their corresponding new forms are:
| Earlier Form | New Form from Tax Year 2026–27 | Nature |
| ------------ | ------------------------------ | ------------------------------------------ |
| Form 24Q | **Form 138** | Salary TDS |
| Form 26Q | **Form 140** | TDS on resident non-salary payments |
| Form 27Q | **Form 144** | TDS on specified payments to non-residents |
| Form 27EQ | **Form 143** | TCS statement |
The Income Tax Department's current guidance confirms that **Form 138 replaces Form 24Q** for salary-related quarterly reporting and **Form 140 replaces Form 26Q** for TDS on non-salary payments to residents. ([Income Tax Department][1])
Therefore, deductors should not automatically use the old 24Q/26Q/27Q/27EQ forms for transactions falling under the new tax year.
---
# Q2 TDS/TCS Return Due Date – 31 October 2026
The second quarter of Tax Year 2026–27 covers:
**1 July 2026 to 30 September 2026**
The quarterly TDS/TCS statement for this period is due on:
### **31 October 2026**
The quarterly cycle for the new regime is:
* **Q1 – April to June:** 31 July 2026
* **Q2 – July to September:** 31 October 2026
* **Q3 – October to December:** 31 January 2027
* **Q4 – January to March:** 31 May 2027
The Income Tax Department's current Form 138 and Form 140 guidance also specifies **31 October** as the Q2 due date. ([Income Tax Department][1])
Businesses should therefore start preparing their Q2 data well before the deadline rather than waiting until the final few days.
---
# Direct TDS Filing on TRACES – What Does It Mean?
Under the reported new workflow, the deductor can access the relevant filing facility through the **TRACES portal** and complete various stages of the quarterly statement process online.
The reported workflow broadly involves:
**TRACES Login → Select Form → Import Challans → Enter/Upload Deductee Details → Map Challans → Validate → E-Verify → File**
This can reduce the number of separate steps involved in preparing and submitting a quarterly statement. ([Casa Huja][2])
The development is particularly useful for businesses that have relatively small or straightforward quarterly TDS statements.
For larger deductors, bulk data preparation and upload may still remain important because manually entering a large number of deductee transactions can be time-consuming.
---
# Is There No Need for the Income Tax e-Filing Portal?
This point requires some care.
The new direct TRACES workflow should not be misunderstood as meaning that the Income Tax e-Filing portal has become irrelevant for all TDS-related compliance.
The Income Tax Department continues to maintain registration and related services for tax deductors and collectors on the e-Filing portal. Its guidance states that a deductor/collector must first be registered on TRACES before registration as a tax deductor or collector on the e-Filing portal. ([Income Tax Department][3])
Therefore, businesses should follow the applicable portal workflow for the particular service they are using rather than assuming that every TDS-related activity has shifted exclusively to TRACES.
The important development for the quarterly statement filing process is the **direct online TRACES workflow available under the new regime**. ([Casa Huja][2])
---
# What Should a Deductor Check Before Filing?
Direct online filing may simplify the submission process, but it does not remove the responsibility of ensuring that the underlying information is correct.
Before filing the Q2 statement, a deductor should carefully check:
### 1. TAN Details
Ensure that the correct TAN is being used and that the deductor's basic registration information is accurate.
### 2. PAN of Deductees
PAN errors can create significant reconciliation problems. Every deductee PAN should be checked carefully.
### 3. Amount Paid or Credited
The amount reported in the quarterly statement should reconcile with the books of account, payroll records, invoices and payment records, as applicable.
### 4. TDS Deducted
The amount of tax deducted should be reconciled with the actual deductions made during the quarter.
### 5. TDS Deposited
The challan information should be checked against the amount actually deposited with the Government.
### 6. Challan Mapping
Correct mapping of challans with deductee transactions is extremely important. Incorrect mapping can lead to unmatched balances and subsequent correction requirements.
### 7. Nature of Payment
The applicable TDS provision and nature of payment should be correctly identified, particularly for payments such as:
* Professional fees
* Contractor payments
* Commission
* Rent
* Interest
* Salary
* Other specified payments
### 8. Lower/Nil Deduction Cases
Where a lower or nil deduction certificate/order is applicable, the relevant information should be reported correctly.
---
# Why the New TRACES Filing Process Can Be Helpful
The direct online workflow has several practical advantages.
## 1. Fewer Separate Steps
A deductor can undertake preparation and filing through the portal instead of depending entirely on an external preparation workflow.
## 2. Better Online Validation
Portal-based validation can help identify certain errors before final submission.
## 3. Easier Challan Management
The reported workflow provides for importing available challans and mapping them against the relevant deductee transactions. ([Casa Huja][2])
## 4. Convenient for Smaller Returns
Businesses with a limited number of TDS transactions may find the online process particularly convenient.
## 5. Digital Verification
The filing process incorporates electronic verification options such as DSC/EVC, subject to the applicable portal requirements.
## 6. Reduced Last-Minute Dependency
An online filing mechanism can help businesses complete routine quarterly compliance without relying entirely on separate file-generation and upload stages.
---
# What About Existing Forms 24Q, 26Q, 27Q and 27EQ?
This is one of the most important points during the transition.
The old forms do **not simply disappear for every historical period**.
For periods governed by the **Income-tax Act, 1961**, including relevant earlier financial years, the old form framework continues to be relevant.
For example, a correction relating to a statement for a period covered by the earlier law should not automatically be filed using the new form number merely because the correction is being made after 1 April 2026.
For new Tax Year 2026–27 statements, however, the new form numbering applies.
The transition can therefore be broadly understood as:
**Earlier periods → Old forms**
**Tax Year 2026–27 onwards → New forms**
This distinction is especially important for tax professionals handling multiple years of TDS corrections.
---
# Form 138 – Earlier Form 24Q
Form 138 is the new quarterly statement corresponding broadly to **Form 24Q**.
It relates to salary TDS reporting and is relevant for employers and other specified deductors covered by the applicable provisions.
The Income Tax Department describes Form 138 as the quarterly statement for reporting TDS deducted on salary, pension or specified interest income cases. ([Income Tax Department][4])
For Q2, covering July to September 2026, the due date is **31 October 2026**.
Employers should reconcile:
* Salary registers
* TDS calculations
* Employee PAN
* Monthly TDS deductions
* Challans
* Employee tax declarations
* Applicable deductions and exemptions
* Quarterly statement data
before submitting the statement.
---
# Form 140 – Earlier Form 26Q
Form 140 broadly replaces **Form 26Q** for TDS on payments other than salary made to residents.
This can cover various business payments where TDS is applicable, including payments such as professional fees, contractor payments, commission, rent and other specified categories.
The Income Tax Department confirms that Form 140 is a quarterly statement for TDS on non-salary payments to residents. ([Income Tax Department][1])
Businesses should therefore pay particular attention to Form 140 while preparing their Q2 compliance.
---
# Form 144 – Earlier Form 27Q
Form 144 relates to TDS on specified payments to non-residents.
Businesses making payments to overseas vendors, consultants or other non-resident recipients should separately examine whether Form 144 applies and whether any treaty-related or documentation requirements are involved.
Non-resident TDS cases can involve additional considerations, so they should not be treated in exactly the same manner as ordinary resident payments.
---
# Form 143 – Earlier Form 27EQ
The quarterly TCS statement has also been renumbered.
**Form 27EQ → Form 143**
For Tax Year 2026–27, the quarterly TCS statement follows the new framework and the Q2 statement is due on **31 October 2026**. ([Kunal Darwani & Co.][5])
This is particularly important because businesses accustomed to the earlier TCS filing calendar should update their compliance calendars for the new regime.
---
# What Happens If the Return Is Filed Late?
Late filing of a TDS/TCS statement can result in a statutory late fee.
Under the new framework, the late fee provisions have also been reorganised. Current professional guidance on Tax Year 2026–27 reports a late fee of **₹200 per day**, subject to the applicable statutory cap. ([SCA][6])
Therefore, deductors should not wait until the final day to begin the filing process.
A portal-related issue, data mismatch or correction requirement near the deadline can consume valuable time.
---
# Practical Checklist for Q2 TDS/TCS Filing
Before filing the Q2 statement, businesses can follow this simple checklist:
☑ Verify TAN
☑ Verify deductee PANs
☑ Reconcile books with TDS records
☑ Check monthly deductions
☑ Verify challans
☑ Reconcile TDS deposited
☑ Check challan mapping
☑ Verify nature of payment
☑ Check lower/nil deduction certificates, wherever applicable
☑ Validate the statement
☑ Complete DSC/EVC verification as applicable
☑ Save/download the acknowledgement/PRN/ARN generated after successful filing
☑ Maintain supporting records for future reference
---
# Don't Wait Until 31 October 2026
Although the statutory deadline for Q2 is **31 October 2026**, businesses should ideally complete their reconciliation and preparation several days before the deadline.
This becomes even more important during a transition year because businesses are dealing with:
* New Income-tax law
* New form numbers
* New terminology
* New filing workflows
* New compliance references
* Historical corrections under the old framework
A simple mistake in form selection or reporting can result in unnecessary correction work later.
---
# Professional TDS & Tax Compliance Support in Moradabad and Kanth and Delhi near by area also
**Shanky Chopra & Associates LLP** provides professional assistance in TDS/TCS compliance, Income Tax matters, GST, ROC compliance, tax notices, appeals, refunds, litigation and other taxation and regulatory matters.
Businesses, employers, firms, professionals and organisations in **Moradabad, Kanth and nearby areas** can obtain assistance with quarterly TDS/TCS return preparation, reconciliation, filing, correction and related compliance documentation.
With the transition to the Income-tax Act, 2025 and the new form structure, professional review can be particularly useful for businesses managing multiple deductees or multiple types of TDS transactions.
---
# Conclusion
The direct TRACES filing workflow represents an important development in TDS/TCS compliance for Tax Year 2026–27. The process can make quarterly filing more convenient by bringing preparation, validation and submission closer together within the TRACES environment. ([Casa Huja][2])
At the same time, businesses should remember that **easy filing does not mean that reconciliation can be skipped**. Accurate PAN details, challan mapping, deduction amounts, payment information and correct form selection remain essential.
For **Q2, July–September 2026**, the key date is:
### 📅 **31 October 2026 – TDS/TCS Statement Due Date**
Businesses should prepare their data early, verify the applicable new form, reconcile the records and complete the filing well before the deadline.
**Stay compliant. Reconcile carefully. File on time.**
*This article is intended for general informational purposes. Taxpayers should verify the applicable provisions and portal instructions for their specific circumstances before filing.*
**TDS Returns Can Now Be Filed Directly on TRACES | Q2 FY 26_27
Learn about direct TDS/TCS filing on TRACES for Tax Year 2026–27, new Forms 138, 140, 143 and 144, Q2 due date of 31 October 2026 and important compliance checks.
Have Questions? We're Here to Help
Get expert advice from SHANKY CHOPRA & ASSOCIATES LLP. Reach out to discuss your requirements.