Rajasthan High Court on Amended Section 147: Reassessment of Subsequently Discovered Escaped Income
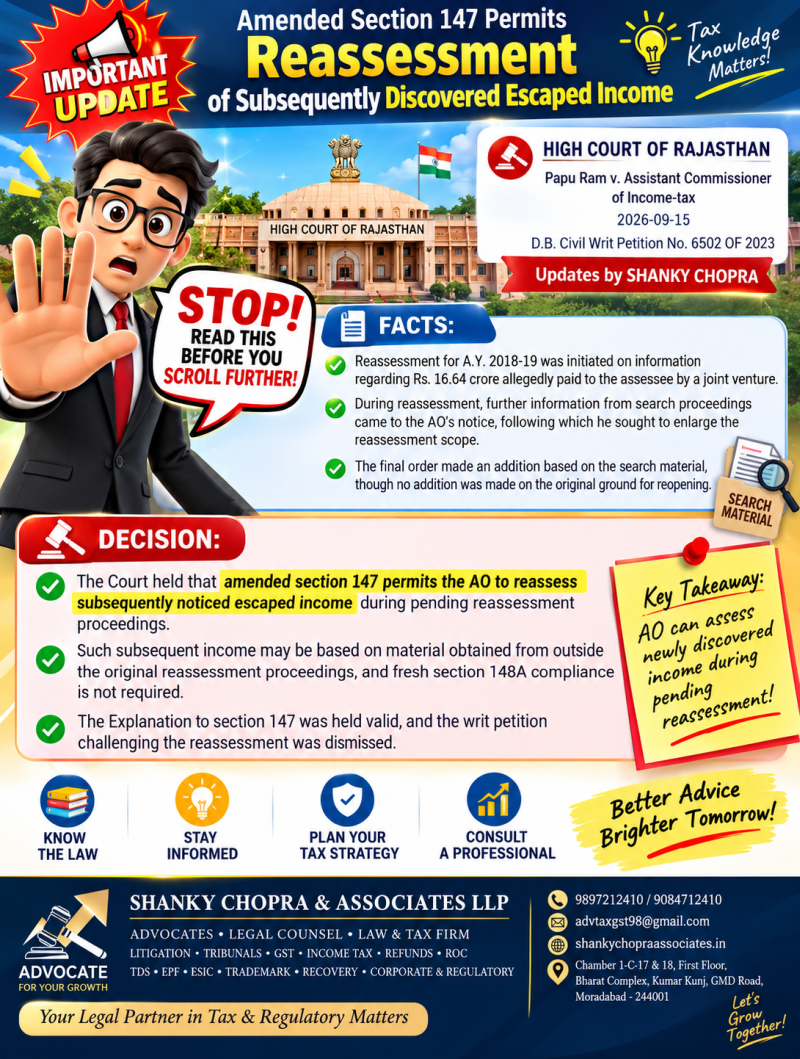
Rajasthan High Court Clarifies Scope of Amended Section 147 for Reassessment of Subsequently Discovered Escaped Income
The Rajasthan High Court, in Papu Ram v. Assistant Commissioner of Income Tax, decided on 15 September 2026, has delivered an important ruling concerning the scope of reassessment proceedings under the amended Section 147 of the Income-tax Act, 1961. The judgment is particularly relevant for taxpayers, Income Tax practitioners, advocates and professionals handling income tax reassessment, Section 148 notices, Section 148A proceedings and tax litigation. (Indian Kanoon)
Background of the Case
The case concerned Assessment Year 2018-19. Reassessment proceedings were initially initiated on the basis of information received from the National E-Statement Centre (NEAC) regarding an amount of approximately ₹16.64 crore allegedly paid to the assessee by a joint venture.
A notice under Section 148A was issued on 17 March 2022, followed by an order under Section 148A(d) and thereafter a notice under Section 148. (Indian Kanoon)
During the reassessment proceedings, the Assessing Officer subsequently received further information/material arising from search proceedings. On the basis of this subsequent information, the AO issued a further show-cause notice and sought to enlarge the scope of the pending reassessment.
Interestingly, the final reassessment order contained an addition based upon the material obtained during the search proceedings, while no addition was ultimately made in respect of the escaped income that had formed the basis of the original reassessment. (Indian Kanoon)
Issue Before the Rajasthan High Court
The principal issue before the Court was whether the Assessing Officer could enlarge an already pending reassessment proceeding by considering subsequently discovered escaped income, including information or material obtained during search proceedings.
The assessee also challenged the Explanation to Section 147, as amended by the Finance Act, 2021, and argued that the pending reassessment should not be enlarged on the basis of information that was not part of the original notice.
Decision of the High Court
The Rajasthan High Court held that the amended Section 147 permits the Assessing Officer to reassess income relating to an issue of escaped assessment that subsequently comes to his notice during the course of reassessment proceedings.
The Court interpreted the Explanation to Section 147 as enlarging the scope of the reassessment provision. According to the judgment, the expression relating to “any issue” concerning escaped income is not restricted only to material that was available when the reassessment proceedings originally commenced. (Indian Kanoon)
The Court further held that, where reassessment proceedings are already pending, subsequently received information can be considered within those proceedings.
Fresh Section 148A Compliance
One of the significant aspects of the judgment concerns Section 148A.
The Court held that in respect of subsequently noticed escaped income during the course of pending reassessment proceedings, a fresh Section 148A proceeding is not required.
The Explanation to Section 147 specifically provides the statutory basis for dealing with such subsequently noticed escaped income without requiring initiation of a fresh Section 148A process. (Indian Kanoon)
Search Material and Pending Reassessment
The judgment is also relevant in cases where search proceedings generate information concerning escaped income.
The Court observed that where reassessment proceedings are already pending, the authorities have two possible courses available:
-
They may enlarge the scope of the pending reassessment on the basis of material obtained during the search concerning escaped income; or
-
They may independently initiate proceedings under the applicable statutory mechanism based on the search material.
The Court held that merely adopting one of these available courses does not, by itself, make the proceedings illegal. (Indian Kanoon)
Validity of Explanation to Section 147
The assessee had also challenged the Explanation to Section 147 as being beyond the legislative framework.
The Rajasthan High Court rejected this challenge and held that the Explanation could not be struck down merely because it broadens the scope of the substantive reassessment provision.
The Court noted that the legislature had consciously retained and modified the Explanation while inserting the amended reassessment framework. The Court therefore gave effect to the legislative language contained in the amended provision. (Indian Kanoon)
What Does This Mean for Taxpayers?
This judgment is important for taxpayers who receive or are already facing Income Tax reassessment proceedings.
Where reassessment has already been validly initiated, the taxpayer should not assume that the AO's examination will necessarily remain confined to the exact information that resulted in the original reopening.
If additional information relating to escaped income subsequently comes to the AO's notice during the reassessment proceedings, the amended Section 147 and its Explanation may permit the AO to examine that additional issue within the pending proceedings.
At the same time, every addition remains subject to the applicable provisions of the Income-tax Act and the facts and circumstances of the individual case. Questions relating to jurisdiction, limitation, relevance of material, statutory procedure, natural justice and the merits of the addition may still require separate examination.
Importance for Income Tax Litigation in Moradabad, Kanth and Delhi
For taxpayers and businesses in Moradabad, Kanth, Delhi and other parts of Uttar Pradesh and India, this judgment is particularly relevant when dealing with reassessment notices and income tax litigation.
Taxpayers receiving notices under Sections 148A or 148, or facing reassessment proceedings where additional information has subsequently been introduced by the Assessing Officer, should carefully examine the complete reassessment record.
Professional review may include examination of:
-
Original information forming the basis of reopening
-
Section 148A notice and order
-
Section 148 notice
-
Subsequent show-cause notices
-
Search or survey-related material
-
Information relied upon by the AO
-
Scope of the reassessment proceedings
-
Proposed additions and supporting evidence
-
Limitation and jurisdiction
-
Principles of natural justice
-
Applicability of the amended Section 147 and its Explanation
Conclusion
The Rajasthan High Court's decision in Papu Ram v. Assistant Commissioner of Income Tax provides an important interpretation of the amended Section 147.
The judgment confirms that, according to the Court's interpretation, subsequently noticed escaped income can be brought within pending reassessment proceedings, including where the subsequent information originates from search material. The Court also held that fresh Section 148A compliance is not required for such subsequently noticed income within the pending reassessment proceedings. (Indian Kanoon)
The writ petition challenging the reassessment and the Explanation to Section 147 was dismissed by the Court. (Indian Kanoon)
Shanky Chopra & Associates LLP provides professional assistance in Income Tax, GST, Reassessment, Tax Appeals, Tax Litigation, Tribunal Matters, Tax Notices and Regulatory Compliance for clients in Moradabad, Kanth, Delhi and across India.
Keywords: Income Tax Reassessment Moradabad, Section 147 Income Tax, Section 148A Reassessment, Section 148 Notice, Income Tax Advocate Moradabad, Tax Consultant Moradabad, Income Tax Lawyer Kanth, Income Tax Litigation Delhi, Tax Litigation Moradabad, Reassessment Proceedings, Escaped Income, Rajasthan High Court Income Tax Judgment.
Have Questions? We're Here to Help
Get expert advice from SHANKY CHOPRA & ASSOCIATES LLP. Reach out to discuss your requirements.