GSTR-3B Return Filing Due Date for September 2026 – GST Compliance Guide
# GSTR-3B Return Filing for September 2026: GST Compliance Guide for Businesses
## Introduction
Goods and Services Tax (GST) compliance is an important responsibility for businesses, traders, manufacturers, service providers and other registered taxpayers in India. Filing GST returns within the applicable time limits helps businesses maintain accurate tax records and meet their statutory obligations. One of the important returns under the GST system is GSTR-3B.
GSTR-3B is a summary return used by applicable registered taxpayers to report details of outward supplies, eligible input tax credit (ITC), tax liability and tax payment. Businesses should review their sales records, purchase invoices, available ITC information and tax calculations before filing the return.
Shanky Chopra & Associates LLP provides GST and taxation consultancy services to businesses and professionals in Delhi, Noida, Meerut, Ghaziabad and Moradabad. This article explains the purpose of GSTR-3B, important filing considerations, reconciliation requirements and practical steps businesses can follow to maintain GST compliance.
## What Is GSTR-3B?
GSTR-3B is a summary GST return in which taxpayers report relevant information about their taxable outward supplies, inward supplies liable to reverse charge where applicable, input tax credit, exempt or non-GST supplies and tax payable.
The information reported in GSTR-3B should be consistent with the taxpayer's books of accounts, sales records, purchase records and other applicable GST returns. Any differences should be examined and corrected in accordance with the applicable GST provisions and return-correction procedures.
Businesses should not treat GSTR-3B as merely a routine monthly form. The figures reported in this return can affect tax payments, ITC utilisation, return reconciliation and departmental scrutiny.
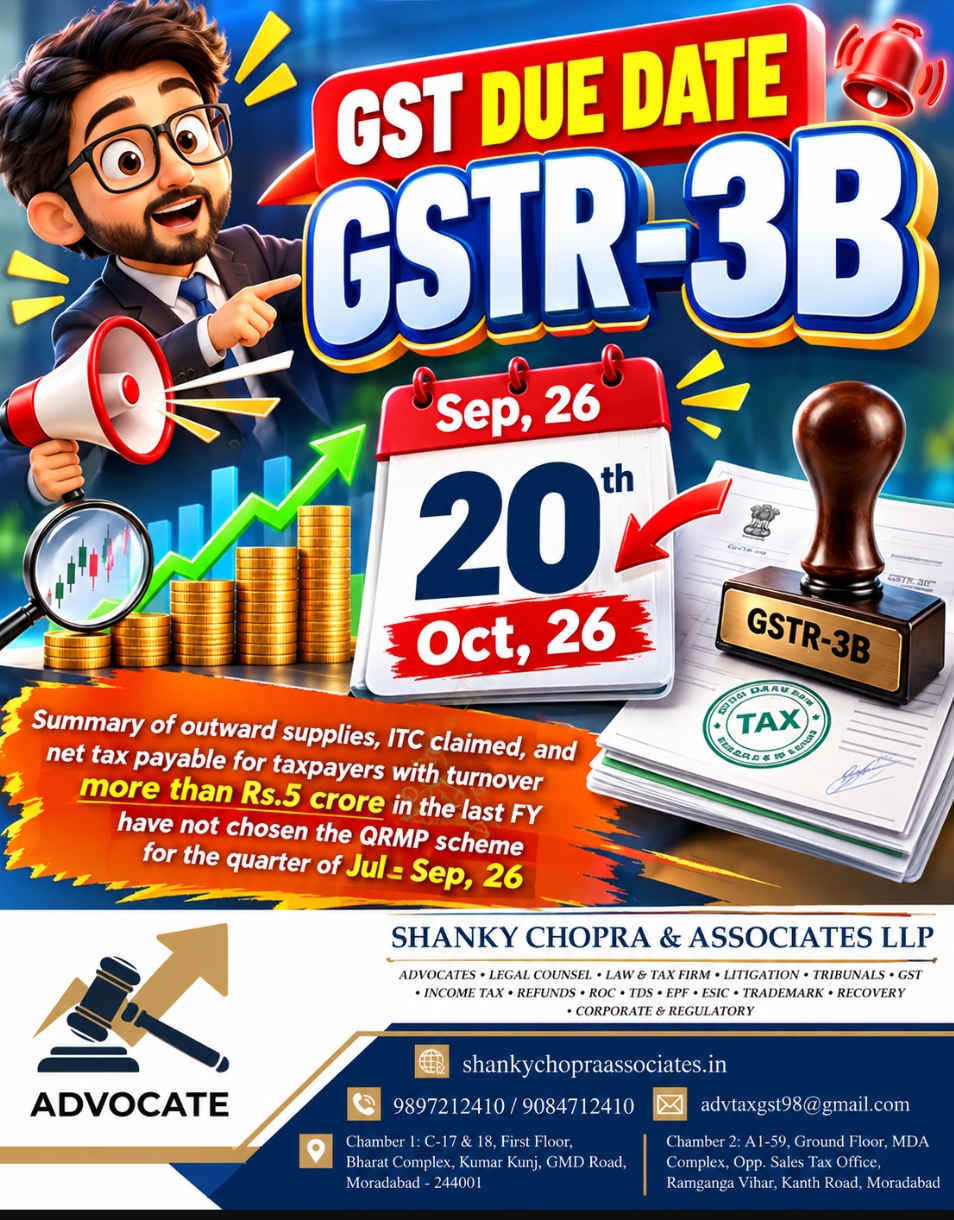
## GSTR-3B Due Date for September 2026
The applicable GSTR-3B due date depends on the taxpayer's filing category and the return-filing scheme applicable to the GST registration. Monthly filers and taxpayers covered under the Quarterly Return Monthly Payment (QRMP) scheme may have different filing schedules.
For the September 2026 tax period, taxpayers should verify the applicable due date on the official GST portal and check whether any notification or extension applies to their category.
Businesses should avoid relying on general online posts without confirming the relevant tax period and filing category. Filing requirements may differ according to the taxpayer's circumstances, and the applicable deadline should always be checked before submission.
## Who Needs to File GSTR-3B?
Registered taxpayers required to furnish GSTR-3B under the applicable GST rules must file the return for the relevant tax period. The filing frequency and reporting obligations depend on the taxpayer's registration status and applicable scheme.
Businesses should review their GST registration details and return dashboard to determine which returns are due. They should also ensure that nil-return requirements, where applicable, are followed correctly.
Even where a business has limited or no taxable transactions during a particular period, it should not assume that no return is required. The taxpayer should confirm the applicable filing obligation on the GST portal.
## Important Details to Check Before Filing GSTR-3B
Before submitting GSTR-3B, businesses should review the following information:
**1. Outward supplies:** Reconcile sales invoices, credit notes, debit notes and other relevant transactions with the sales ledger and GSTR-1.
**2. Input tax credit:** Verify ITC eligibility, supporting documents and the information available in GSTR-2B. ITC should be claimed only when the applicable statutory conditions are satisfied.
**3. Reverse charge liability:** Identify purchases or services for which GST may be payable under the reverse charge mechanism.
**4. Tax liability:** Calculate the applicable IGST, CGST, SGST or UTGST and cess, wherever relevant.
**5. Interest and late fees:** Check whether any interest or late fee is payable under the applicable provisions.
**6. Electronic ledgers:** Review the electronic credit ledger, electronic cash ledger and electronic liability register before completing the filing process.
A proper review helps identify errors before the return is submitted.
## Importance of GSTR-1 and GSTR-3B Reconciliation
GSTR-1 generally contains details of outward supplies, while GSTR-3B reports summary figures and tax liabilities. Businesses should reconcile the two returns to identify differences in taxable turnover, tax rates, amendments, credit notes and other relevant details.
Differences may arise because of reporting mistakes, incorrect invoice classification, amendments, timing differences or other transaction-specific reasons. Each difference should be investigated using the underlying records.
If an invoice has been incorrectly classified or reported, the taxpayer should examine the applicable correction mechanism and reporting period. Any correction should be made in accordance with the GST law and portal procedures.
Maintaining a proper reconciliation statement with supporting documents can help businesses explain differences during departmental verification.
## Input Tax Credit Verification and GSTR-2B
Input tax credit is an important part of GST compliance because eligible credit can reduce the amount of output tax payable, subject to applicable restrictions and conditions.
Before claiming ITC in GSTR-3B, businesses should examine purchase invoices, debit notes, supplier details, accounting records and GSTR-2B. They should also verify the statutory eligibility of the credit and any applicable restrictions.
A difference between GSTR-2B and the ITC recorded in the books does not automatically establish that every difference is eligible or ineligible. The reason for each difference should be identified and documented.
Businesses should maintain supplier-wise reconciliation statements, copies of invoices and other relevant evidence. Where a discrepancy is identified, the taxpayer should evaluate the correct treatment under the applicable GST provisions instead of making an unsupported adjustment.
## Common Mistakes in GSTR-3B Filing
Some common issues that businesses should avoid include:
- Reporting incorrect taxable turnover.
- Using an incorrect GST rate or tax classification.
- Claiming ITC without verifying eligibility.
- Failing to identify reverse charge liability.
- Reporting differences between GSTR-1 and GSTR-3B without reconciliation.
- Overlooking amendments, credit notes or debit notes.
- Incorrectly calculating interest or late fees.
- Filing the return without checking the available electronic ledgers.
A systematic review before filing can reduce avoidable mistakes. Businesses should preserve relevant working papers and supporting documents for future reference.
## What Happens If GSTR-3B Is Filed Late?
Late filing can lead to consequences under the applicable GST provisions, including late fees and interest where legally applicable. The amount payable depends on the nature of the delay, the taxpayer's circumstances and the relevant statutory provisions.
Businesses should check the portal for outstanding returns, dues and other compliance requirements. If a delay has occurred because of a technical issue, taxpayers should preserve relevant grievance references, screenshots, portal communications and other supporting evidence.
However, a portal issue should not automatically be assumed to remove every statutory consequence. The facts, applicable provisions and available evidence should be examined before making a representation to the department.
## GST Notice Replies, Appeals and Compliance Support
GST-related issues may arise from differences in turnover, ITC mismatches, tax-rate disputes, interest calculations or delayed return filing. When a notice is received, the taxpayer should carefully examine the period involved, the legal provisions cited, the calculation of the demand and the evidence relied upon by the department.
A well-prepared reply should address the specific allegations, explain the relevant facts, provide supporting documents and present the applicable legal grounds. If an adverse order has been passed, the availability of an appeal or another appropriate remedy should be assessed according to the facts and statutory timelines.
Shanky Chopra & Associates LLP assists businesses with GST return filing, reconciliation, departmental replies, appeals, refund matters and related taxation compliance, depending on the requirements of each case.
## GST and Tax Consultancy Services in Delhi NCR and Western Uttar Pradesh
Businesses often need professional assistance with GST returns, accounting reconciliation, tax notices and recurring statutory compliance. A structured compliance process can help them maintain better records and identify issues at an early stage.
Shanky Chopra & Associates LLP provides taxation consultancy support for businesses and professionals in the following locations:
**Delhi:** GST return filing, reconciliation and taxation-related assistance for eligible business requirements.
**Noida:** GST compliance, ITC verification, return preparation and related consultancy services.
**Meerut:** GST registration support, return filing, tax reconciliation and assistance with departmental matters.
**Ghaziabad:** GST returns, taxation compliance, notice replies and other relevant professional services.
**Moradabad:** GST return filing, GST reconciliation, income tax returns, TDS compliance and related taxation consultancy.
Services are provided according to the client's requirements, applicable law and the scope of professional engagement. Businesses should provide accurate records and relevant documents to enable proper examination of their compliance matters.
## How Businesses Can Improve GST Compliance
Businesses can adopt a practical process to improve the accuracy of their GST filings.
First, maintain updated sales and purchase records. Record invoices, credit notes, debit notes and other relevant transactions promptly.
Second, reconcile the books of accounts with GSTR-1, GSTR-3B and available ITC information at regular intervals. Do not wait until the filing deadline to identify major discrepancies.
Third, maintain a calendar of applicable return due dates and assign responsibility for reviewing and filing returns.
Fourth, verify the tax rates, place of supply, classification and tax treatment of transactions where required.
Fifth, preserve supporting documents, reconciliations, payment challans and acknowledgements after filing.
Finally, seek professional advice when the transaction involves a complex tax treatment, an ITC dispute, a departmental notice or a significant reconciliation difference.
## Conclusion
GSTR-3B is an important part of GST compliance for applicable registered taxpayers. Accurate reporting, timely filing, ITC verification and reconciliation with other GST records can help businesses maintain reliable tax records and address discrepancies more effectively.
For September 2026, taxpayers should confirm their applicable filing deadline through the official GST portal and complete the necessary checks before submitting their return.
Shanky Chopra & Associates LLP offers GST and taxation consultancy services for businesses in Delhi, Noida, Meerut, Ghaziabad and Moradabad. For assistance with GST return filing, ITC reconciliation, GST notices, appeals and related tax compliance, businesses may contact the firm to discuss their specific requirements.
**Contact Shanky Chopra & Associates LLP**
Website: https://shankychopraassociates.in
Phone: 9897212410 / 9084712410
Email: advtaxgst98@gmail.com
Office: Moradabad, Uttar Pradesh
*Disclaimer: This article is intended for general informational purposes only. GST provisions and filing requirements may change. Taxpayers should verify the latest applicable rules, notifications and due dates through official sources before acting.*
Have Questions? We're Here to Help
Get expert advice from SHANKY CHOPRA & ASSOCIATES LLP. Reach out to discuss your requirements.