# GST Due Dates for October 2026:
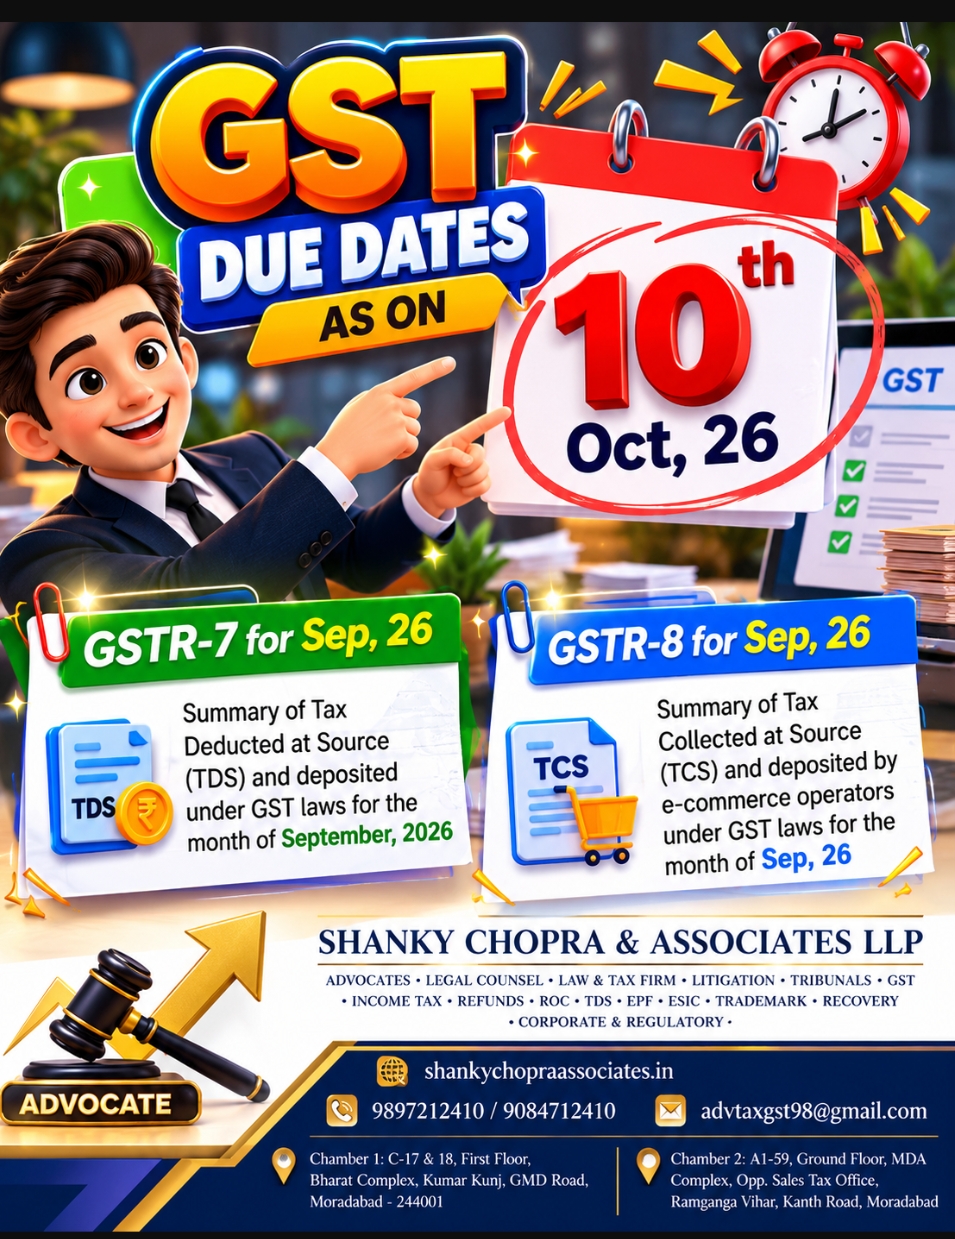
# GST Due Dates for October 2026: GSTR-7 and GSTR-8 Filing for September 2026
**Published by: Shanky Chopra & Associates LLP | Advocates, Legal Counsel & Tax Consultants**
GST compliance is an important responsibility for businesses, government departments and e-commerce operators in India. Every registered person must understand the applicable return filing requirements and complete the necessary formalities within the prescribed time. For October 2026, taxpayers should pay particular attention to the GST return filing deadlines applicable to the September 2026 tax period.
The two important returns covered in this article are **GSTR-7 and GSTR-8**, which relate to Tax Deducted at Source (TDS) and Tax Collected at Source (TCS), respectively, under GST law.
## GST Due Dates for October 2026
The following table provides the standard statutory due dates for the September 2026 tax period.
| GST Return | Applicable Tax Period | Standard Due Date |
| ---------- | --------------------- | ----------------- |
| GSTR-7 | September 2026 | 10 October 2026 |
| GSTR-8 | September 2026 | 10 October 2026 |
These dates are based on the standard statutory filing schedule. Taxpayers should check the official GST portal and applicable government notifications for any changes, extensions or special instructions.
## 1. What Is GSTR-7?
GSTR-7 is a monthly GST return applicable to registered persons who are required to deduct tax at source under Section 51 of the Central Goods and Services Tax Act, 2017, and the corresponding provisions of applicable State GST laws.
Certain government departments, local authorities, governmental agencies and other notified persons may be required to deduct GST TDS when making payments to suppliers, subject to the applicable statutory conditions.
The purpose of GSTR-7 is to report the relevant details of tax deducted at source, the suppliers concerned and the amounts deposited with the government.
### Who Needs to File GSTR-7?
Persons required to deduct GST TDS under the applicable provisions must comply with the registration, deduction, payment and return filing requirements.
Before filing, the deductor should verify whether the transaction falls within the scope of Section 51 and whether the applicable conditions, thresholds and exceptions are satisfied.
### Important Information Required for GSTR-7
The deductor should keep the following information ready:
* GSTIN and other registration details.
* Details of suppliers from whom tax has been deducted.
* Relevant invoices and payment records.
* Taxable amounts and applicable TDS calculations.
* Details of tax deducted and deposited.
* Electronic cash ledger and payment information.
* Invoice-level details required by the applicable return format.
From the September 2025 tax period onwards, invoice-wise reporting functionality was introduced for GSTR-7 on the GST portal. Deductors should therefore maintain appropriate invoice-level records while preparing their returns.
## 2. What Is GSTR-8?
GSTR-8 is a monthly statement required to be furnished by e-commerce operators who are liable to collect tax at source under Section 52 of the CGST Act, 2017, and corresponding provisions of applicable GST laws.
E-commerce operators facilitate supplies of goods or services through electronic platforms. Where the statutory conditions for TCS apply, the operator must collect the applicable amount and report the prescribed transaction details.
GSTR-8 enables the reporting of relevant supplies made through the electronic commerce platform, supplies returned and the amount collected as TCS.
### Who Is Required to File GSTR-8?
E-commerce operators who are required to collect TCS under Section 52 must comply with the applicable statement filing requirements.
The obligation depends on the operator's role and the relevant statutory provisions. Businesses selling products online should determine whether they are acting as suppliers through a platform or as the e-commerce operator responsible for collecting TCS.
Merely selling goods online does not automatically mean that every seller must file GSTR-8. The applicable compliance responsibility must be identified correctly.
### Records Required for GSTR-8
Before preparing GSTR-8, e-commerce operators should reconcile:
* GSTIN and registration information.
* Details of suppliers using the platform.
* Taxable supplies facilitated through the platform.
* Details of supplies returned, wherever applicable.
* TCS collected during the relevant month.
* Relevant adjustments and transaction records.
* Amounts payable and payment information.
Accurate reconciliation helps reduce the possibility of incorrect reporting and subsequent discrepancies.
## 3. How to File GSTR-7 and GSTR-8 Online
Both returns are filed electronically through the GST portal. Taxpayers should use the appropriate login credentials and ensure that the return is prepared for the correct tax period.
The general filing process is as follows:
**Step 1: Log in to the GST portal**
Visit the official website at https://www.gst.gov.in and log in using the relevant GST credentials.
**Step 2: Open the Returns Dashboard**
Select the applicable financial year, return period and return form. For the current filing cycle, select September 2026.
**Step 3: Prepare the return**
Enter or verify the prescribed details, including supplier information, transaction values, tax deductions or collections and other applicable particulars.
**Step 4: Reconcile the information**
Compare the figures reported in the return with the relevant invoices, books of accounts, payment records and supporting documents.
**Step 5: Pay the applicable amount**
Where an amount is payable, ensure that the payment and ledger requirements are completed in accordance with the applicable provisions.
**Step 6: Submit and file the return**
Review the information carefully, submit the return and complete the required filing and authentication process.
**Step 7: Save the acknowledgement**
Download or retain the filed return, acknowledgement and relevant payment records for future reference.
The exact portal options may vary according to the return form and functionality available at the time of filing.
## 4. What Happens If GSTR-7 or GSTR-8 Is Filed Late?
Failure to comply with GST return filing requirements may lead to late fees and other consequences under the applicable law.
For GSTR-7, taxpayers should examine Section 47 of the CGST Act, relevant notifications and the applicable late-fee provisions. A waiver or special relief may apply in particular circumstances, including specified cases where no TDS was deducted, subject to the conditions of the relevant notification.
For GSTR-8, the applicable statutory provisions and the consequences of delayed filing should be examined separately. The legal position for one return should not automatically be applied to the other.
Taxpayers should not assume that a return is exempt from filing merely because there were no transactions during a particular period. The obligation to file a nil return or statement must be assessed under the provisions applicable to the relevant form.
Where a return has already become overdue, the taxpayer should review the pending period, applicable fees and any available statutory relief before completing the filing.
## 5. Common Mistakes to Avoid While Filing GST Returns
Even experienced businesses may face compliance problems because of incorrect data, incomplete reconciliation or misunderstanding of their obligations.
The following precautions are recommended:
**Incorrect GSTIN:** Verify the GSTIN of each supplier before reporting the transaction.
**Wrong tax period:** Ensure that the return relates to September 2026 and not another month.
**Incorrect TDS or TCS calculation:** Check the applicable taxable value, statutory conditions and calculation method.
**Missing invoice details:** Maintain the invoice-level information required under the applicable return format.
**Mismatch with accounting records:** Reconcile the return with books of accounts, invoices and payment records.
**Incomplete filing:** Saving or preparing a return on the portal is not necessarily the same as successfully filing it. Check the filing status and retain the acknowledgement.
**Ignoring notifications:** Due dates, return formats and compliance procedures may change through government notifications or portal updates. Always verify the latest applicable requirements.
## 6. Why GST Compliance Is Important for Businesses
Timely and accurate GST compliance supports proper accounting, transparent transaction reporting and better record management.
For government contractors and other entities required to deduct GST TDS, correct reporting helps ensure that deductions are properly documented and reflected against the relevant suppliers.
For e-commerce operators, accurate TCS reporting assists in reconciling transactions facilitated through their platforms and maintaining appropriate compliance records.
Businesses should establish a monthly compliance calendar, assign responsibility for preparing returns and maintain supporting documentation. A systematic approach reduces the risk of missed deadlines, avoidable errors and unnecessary correspondence with tax authorities.
## 7. Professional GST Services in Moradabad, Kanth and Delhi
Shanky Chopra & Associates LLP provides professional assistance in GST, taxation, corporate compliance and legal matters for businesses and professionals.
Our services include:
* GST registration and return filing.
* GSTR-1 and GSTR-3B compliance.
* GSTR-7 and GSTR-8 filing assistance.
* GST reconciliation and audit support.
* GST notices, replies and departmental proceedings.
* GST appeals, refunds and litigation support.
* Income Tax Return filing and tax advisory.
* TDS compliance and related documentation.
* ROC filings and corporate regulatory compliance.
* Company and LLP-related legal services.
* Trademark registration and related assistance.
We assist traders, manufacturers, contractors, service providers, e-commerce businesses and other eligible taxpayers with their GST and taxation requirements.
Our objective is to help clients understand their compliance obligations, maintain accurate records and address tax-related issues through appropriate professional guidance.
## 8. Frequently Asked Questions
**Q1. What is the due date for GSTR-7 for September 2026?**
The standard statutory due date is 10 October 2026, subject to any applicable government notification or extension.
**Q2. What is the due date for GSTR-8 for September 2026?**
The standard statutory due date is also 10 October 2026, subject to any applicable change notified by the government.
**Q3. Is GSTR-7 applicable to every GST-registered business?**
No. GSTR-7 applies to persons required to deduct GST TDS under the relevant statutory provisions.
**Q4. Is every online seller required to file GSTR-8?**
No. GSTR-8 is generally applicable to e-commerce operators required to collect TCS under Section 52. The obligation should be determined according to the role of the business and applicable law.
**Q5. Where can taxpayers file these returns?**
Eligible taxpayers can access the official GST portal at https://www.gst.gov.in.
**Q6. Should the due date be verified before filing?**
Yes. Taxpayers should check the official portal and applicable notifications for any extension, change or special instruction.
## Conclusion
The October 2026 GST compliance calendar includes the standard due dates for GSTR-7 and GSTR-8 relating to September 2026, both falling on 10 October 2026 under the normal statutory schedule.
Persons responsible for GST TDS and e-commerce operators liable for GST TCS should prepare their records in advance, reconcile the relevant figures and complete the filing process within the applicable time limit.
For professional assistance with GST returns, reconciliation, notices, appeals, refunds and taxation matters, contact **Shanky Chopra & Associates LLP, Advocates & Tax Consultants**.
Website: https://shankychopraassociates.in
Have Questions? We're Here to Help
Get expert advice from SHANKY CHOPRA & ASSOCIATES LLP. Reach out to discuss your requirements.