CBDT Notifies New Rule 281A and Form 173A for Tax Exemption on Government Securities
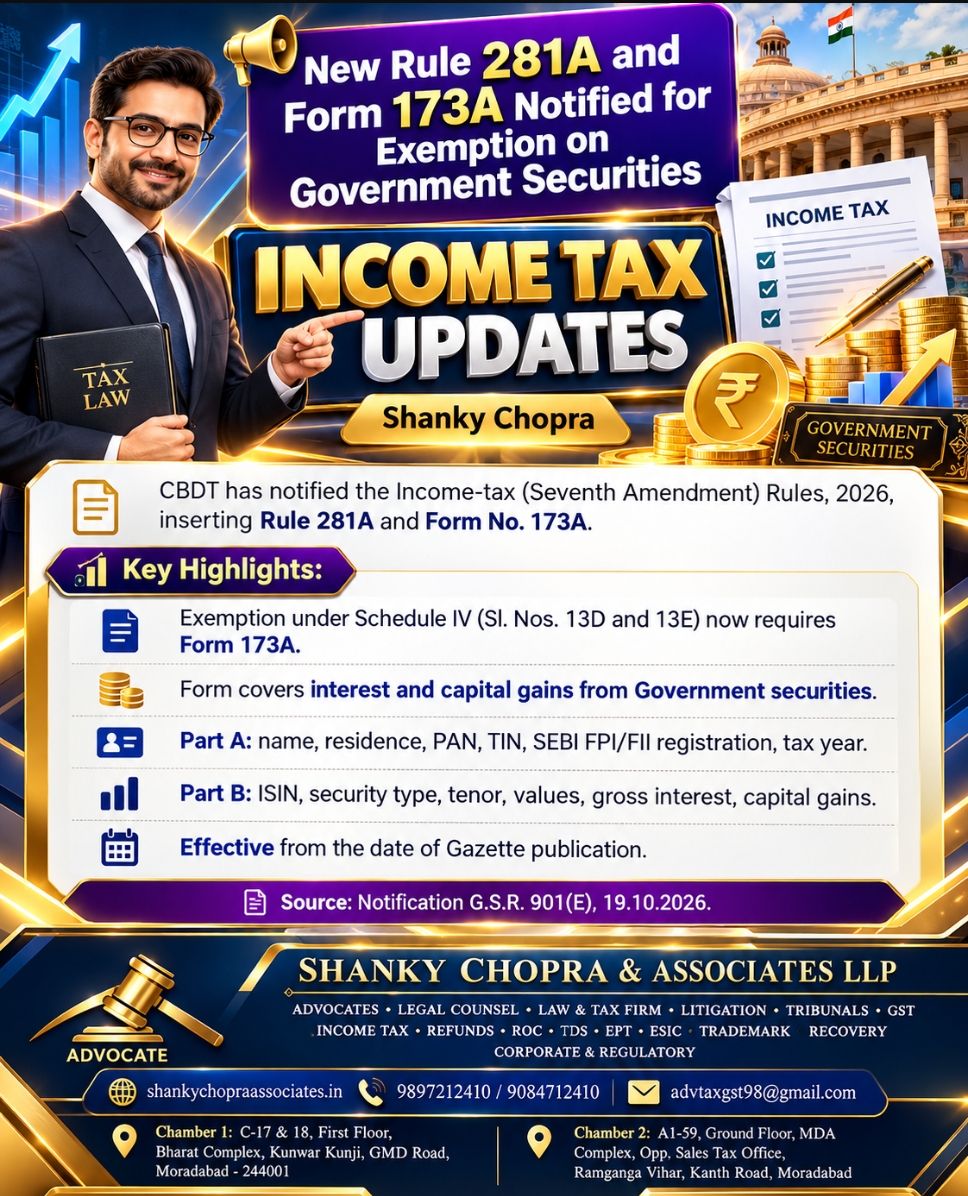
CBDT Introduces Rule 281A and Form 173A: New Income Tax Compliance for Government Securities in 2026
Published Date: 23 October 2026
The Central Board of Direct Taxes (CBDT) has introduced an important amendment to the Income-tax Rules, 2026, through the Income-tax (Seventh Amendment) Rules, 2026. The amendment introduces a new Rule 281A and Form No. 173A for furnishing information when claiming specified tax exemptions on interest income and capital gains arising from Government securities.
The amendment was notified through Notification No. 137/2026, G.S.R. 901(E), dated 19 October 2026. It came into force on the date of publication in the Official Gazette. The new requirement is relevant to taxpayers claiming exemptions under Serial Numbers 13D and 13E of Schedule IV of the Income-tax Act, 2025.
This article explains the new rule, the purpose of Form 173A, the information required, eligibility considerations and practical compliance steps for taxpayers and tax professionals.
1. What Is Rule 281A Under the Income-tax Rules, 2026?
Rule 281A has been inserted after Rule 281 of the Income-tax Rules, 2026. It prescribes the information-furnishing requirement for claiming exemptions under Schedule IV, Table Serial Numbers 13D and 13E of the Income-tax Act, 2025.
Under the new rule, an assessee claiming an exemption under these specified entries must furnish information in Form No. 173A.
The primary purpose of this amendment is to establish a prescribed reporting mechanism for relevant exemption claims involving Government securities.
Taxpayers should understand that Rule 281A is a procedural compliance requirement. It does not independently grant a tax exemption to every person who invests in Government securities. The underlying exemption remains subject to the relevant statutory provisions and eligibility conditions.
2. What Is Form No. 173A?
Form No. 173A is titled “Information to be furnished for claiming exemption on interest and capital gains from Government securities.”
It has been prescribed to collect information about the taxpayer claiming the exemption, the Government securities held, transactions undertaken during the tax year and the income associated with those securities.
The form is divided into two main parts:
Part A: Basic information about the taxpayer.
Part B: Details of Government securities and the relevant income.
The form also includes a declaration confirming that the information furnished is true to the best of the declarant's knowledge and belief and is consistent with the applicable legal provisions.
3. Who Needs to Furnish Form 173A?
Form 173A applies to taxpayers claiming exemptions under Serial Numbers 13D and 13E of Schedule IV of the Income-tax Act, 2025.
The relevant exemption provisions must be examined before determining whether a taxpayer is required to furnish the form. The amendment is particularly relevant to specified eligible foreign institutional investors and the Bank for International Settlements, subject to the applicable statutory conditions.
The requirement should not be interpreted as applying automatically to every Government securities investor.
For example, an ordinary resident individual who invests in Government bonds through a bank should not assume that Form 173A is required merely because the investment generates interest income.
Similarly, foreign investors must verify the relevant eligibility conditions rather than assuming that all foreign investors qualify for the exemptions.
4. Part A: Basic Information Required in Form 173A
Part A collects identification and contact information about the person or entity claiming the exemption.
The prescribed information includes the following:
Name: The full name of the taxpayer or relevant entity must be provided.
Country of Residence: The country in which the taxpayer is resident for the relevant purpose.
Address: The address in the country of residence or the headquarters address, as applicable. The prescribed notes require sufficient address details, including the country, building or flat, street, postal code, locality, district and state.
Permanent Account Number (PAN): The taxpayer's PAN, where applicable under the prescribed form.
Tax Identification Number (TIN): The tax identification number issued in the country of residence.
SEBI Registration Number: The registration number as a Foreign Portfolio Investor (FPI) or Foreign Institutional Investor (FII), where applicable.
Tax Year: The tax year for which the exemption is being claimed.
Email Address and Contact Number: Contact details for identification and communication.
The form specifically provides that the TIN and SEBI registration details mentioned in items 1(v) and 1(vi) are optional for the Bank for International Settlements (BIS).
5. Part B: Details of Government Securities
Part B contains security-wise information relating to the exemption claim. This enables the relevant investment and income details to be reported in a structured format.
The form requires the following information.
International Securities Identification Number (ISIN)
An ISIN is a unique identification code assigned to a particular security. It helps identify the Government security to which the reported investment and income relate.
Type of Government Security
The form lists the following categories:
Treasury Bills
Fixed-rate bonds
Floating-rate bonds
State Development Loans (SDLs)
Other securities, where applicable and specified
The appropriate category should be selected according to the security concerned.
Tenor of the Security
Tenor refers to the period or maturity term of the security. The relevant details should be reported accurately using the taxpayer's investment records.
Value of Securities on 1 April
The form asks for the total value of securities held as on 1 April of the relevant tax year.
Purchases During the Year
The value of Government securities purchased during the tax year must be reported.
Sale Consideration
Where securities have been sold during the year, the sale consideration must be reported as prescribed.
Value of Securities on 31 March
The closing value of the relevant securities as on 31 March must be furnished.
Gross Interest Received or Accrued
The form requires the gross amount of interest received or accrued during the tax year. Taxpayers should reconcile this figure with their investment statements and other relevant records.
Capital Gains Earned
Capital gains earned during the tax year must also be reported. The applicable computation and exemption treatment should be determined under the relevant provisions of tax law.
The form permits the security-wise details to be repeated where required. Amounts are generally required to be reported in Indian rupees unless otherwise provided.
6. Why Is This Information Important?
Government securities may generate interest income and, depending on the transaction and applicable tax provisions, capital gains when sold or transferred.
For an eligible taxpayer claiming a specified exemption, accurate reporting is important for several reasons.
First, it identifies the securities associated with the exemption claim. Second, it provides information about investment holdings and transactions during the relevant tax year. Third, it helps establish the relationship between the reported securities and the interest or capital gains for which relief is claimed.
Maintaining consistent records can also help taxpayers respond to questions about their exemption claims and reconcile the information furnished in the prescribed form with their investment statements.
7. Effective Date of the Amendment
The Income-tax (Seventh Amendment) Rules, 2026, were notified on 19 October 2026 through Notification No. 137/2026, G.S.R. 901(E).
The notification states that the amendment comes into force on the date of publication in the Official Gazette.
Accordingly, the amendment became effective on 19 October 2026.
Taxpayers and professionals should refer to the original notification and applicable administrative instructions for any additional filing procedures or deadlines relevant to a particular claim.
8. Practical Compliance Checklist for Tax Professionals
Tax professionals advising clients on these exemptions should consider the following steps:
Verify eligibility: Confirm that the taxpayer falls within the scope of the relevant exemption provisions under Schedule IV, Serial Numbers 13D and 13E.
Review the securities: Obtain the necessary investment statements and identify each relevant Government security by its ISIN.
Reconcile transactions: Match opening holdings, purchases, sales and closing holdings with the available investment records.
Verify income details: Reconcile gross interest received or accrued and capital gains with the applicable records and computations.
Check taxpayer information: Confirm the accuracy of the name, address, PAN, TIN, registration details and tax year, as relevant.
Complete the prescribed form: Furnish the information required by Form 173A and review the declaration before submission.
Retain supporting records: Keep relevant investment statements, transaction details and income computations available for verification.
Confirm filing requirements: Check the official instructions and applicable filing mechanism before advising the taxpayer on the method and timing of submission.
These steps are intended as a practical checklist. Any additional document, deadline or procedural requirement should be confirmed from the applicable rules or official instructions.
9. Does Form 173A Create a New Tax or Exemption?
The amendment primarily introduces an information-furnishing requirement for specified exemption claims.
It should not be confused with the introduction of a new tax on all Government securities, nor should it be interpreted as a blanket exemption for all investors.
Whether interest income or capital gains qualify for exemption depends on the relevant statutory entry and the taxpayer's circumstances. Furnishing the form does not, by itself, establish eligibility or guarantee acceptance of the exemption claim.
Ordinary investors should continue to determine the tax treatment of their Government securities under the provisions applicable to their investments.
10. Important Considerations for Foreign Investors
Foreign investors and specified institutions should review their eligibility and reporting obligations carefully.
They should ensure that the information furnished in Form 173A is consistent with their investment records, tax identification details and relevant registration information. Where an institution has a principal officer or another authorised representative responsible for the declaration, the applicable authorisation and signatory requirements should also be verified.
The special provision allowing certain details to be optional for the Bank for International Settlements should not be extended to other taxpayers without legal support.
Conclusion
The introduction of Rule 281A and Form No. 173A under the Income-tax (Seventh Amendment) Rules, 2026, establishes a prescribed reporting mechanism for specified exemption claims relating to interest and capital gains from Government securities.
The new form collects taxpayer identification details, security-wise investment information, purchase and sale values, interest income and capital gains for the relevant tax year.
Taxpayers should first verify whether they qualify under the specified provisions of Schedule IV before preparing or submitting the form. Accurate reporting, proper reconciliation and compliance with the applicable legal requirements remain essential.
Official Reference: CBDT Notification No. 137/2026, G.S.R. 901(E), dated 19 October 2026.
Disclaimer: This article is for general informational purposes only and should not be treated as individual tax or legal advice. The applicable statutory provisions, notification and official instructions should be reviewed before claiming an exemption.
Published by Shanky Chopra & Associates LLP
Taxation Advocates and Consultants
GST | Income Tax | Appeals | Refunds | TDS | ROC Compliance | Corporate Legal Services
Have Questions? We're Here to Help
Get expert advice from SHANKY CHOPRA & ASSOCIATES LLP. Reach out to discuss your requirements.